
Financing Begins Long Before the Loan Application
Small Gains Don’t Look Impressive—Until They Win the Game
August 18, 2026
Follow-Up Is the Commitment. Follow-Through Is the Differentiator
September 9, 2026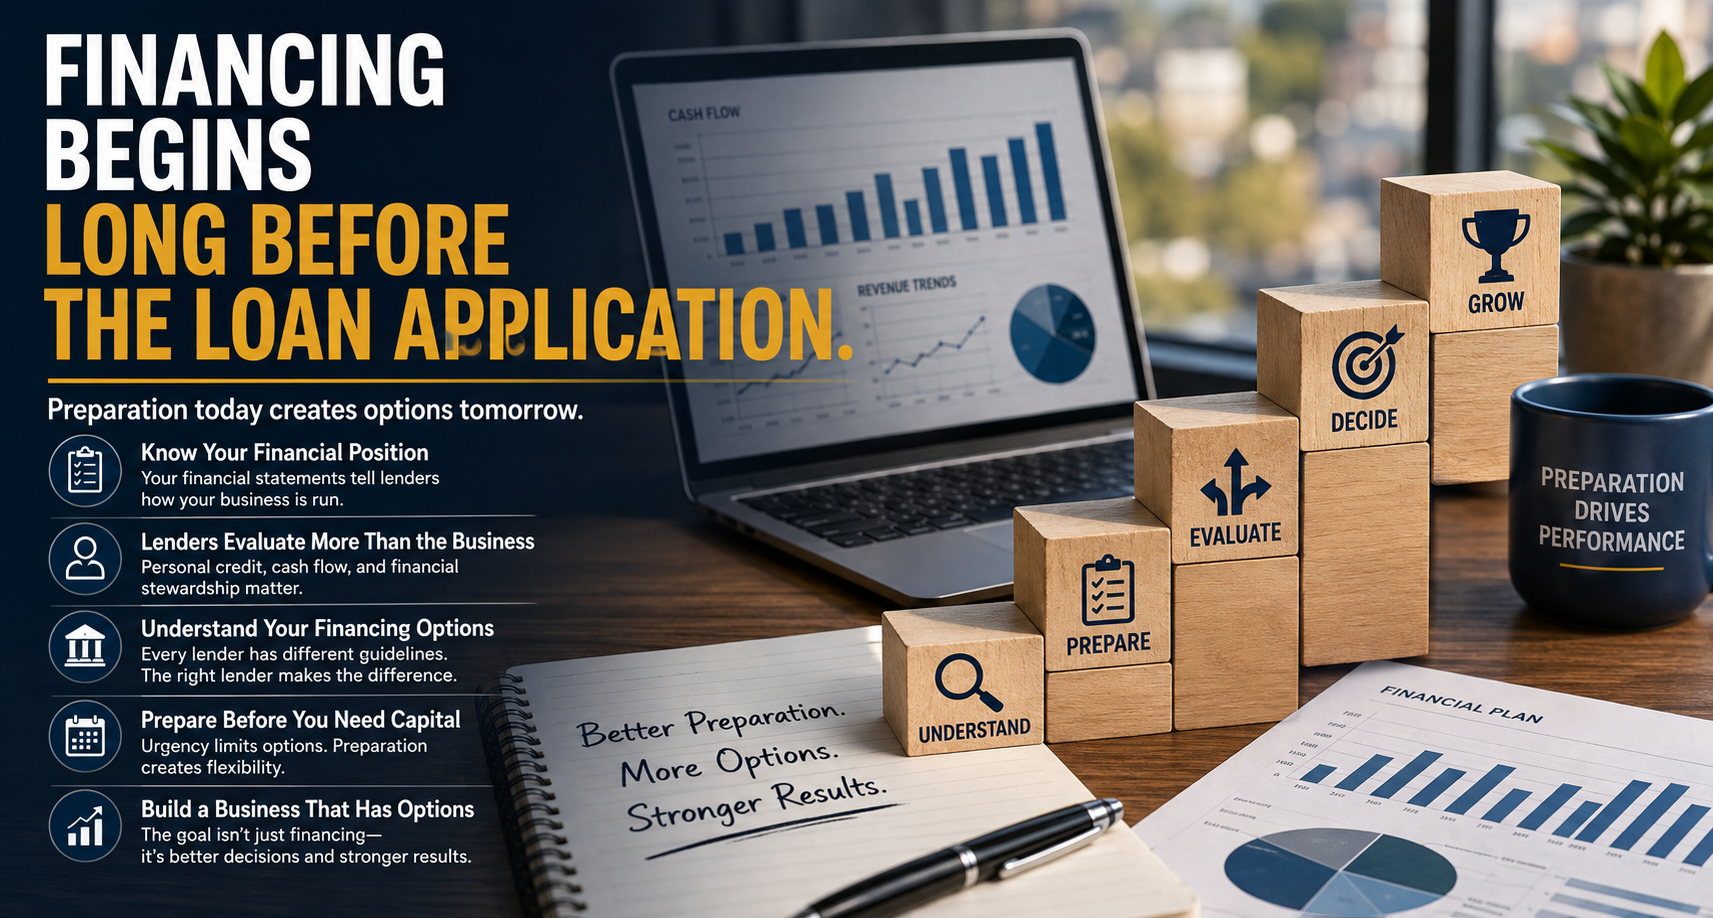
What Every Business Owner Should Know Before Seeking Business Financing
For many business owners, the search for financing begins with a phone call to the bank.
Unfortunately, that’s frequently too late.
Whether you’re purchasing equipment, increasing working capital, expanding operations, acquiring commercial real estate, or pursuing a larger project, the financing process doesn’t begin when you submit an application—it begins long before a lender ever reviews your financial statements.
After more than 15 years helping businesses secure financing nationwide, I’ve seen one truth repeated time and again: profitable companies are sometimes declined for financing, while other businesses with similar financial performance receive approvals.
The difference is rarely found in a single document. More often, it’s found in preparation.
This is one reason I view business finance as part of a much larger preparation-driven approach to organizational performance. The financial decisions a company can make tomorrow are often being shaped by the decisions it makes today.
The businesses that consistently obtain financing understand something many owners overlook: lenders are not simply evaluating whether you need the money. They are evaluating how effectively your company will utilize the funds and whether the business has the financial capacity to adhere to the proposed repayment terms.
Your Financial Statements Tell a Story
Many business owners assume collateral is the lender’s primary concern.
Collateral certainly matters, but it is only one part of a much larger picture. From the borrower’s perspective, collateral should be viewed as protection for the lender if the loan is not repaid according to its terms. Like any form of insurance, that is important to have in place, no one expects or wants to rely on it.
Your financial statements, tax returns, credit history, cash flow, debt obligations, and management practices collectively tell lenders how your business operates and how it responds to opportunity, risk, and change.
One of the most common challenges I encounter involves profitability.
Business owners frequently work with accountants whose primary objective is minimizing income taxes. While that strategy may reduce today’s tax liability, it can unintentionally reduce tomorrow’s borrowing capacity.
From a lender’s perspective, your federal tax returns often become the official scorecard of your business. Internal financial statements are important, but lenders typically place significant weight on the financial performance reported to the Internal Revenue Service.
Simply put, your business is often evaluated by what your records demonstrate—not by what you know your business is capable of achieving.
Lenders Evaluate More Than the Business
Many business owners are surprised to discover that lenders evaluate not only the business, but also the person behind it.
Personal credit history, personal financial statements, global cash flow, existing obligations, and management experience can all contribute to the lending decision.
For privately held companies, lenders frequently ask business owners to personally guarantee the loan. That means your personal financial picture becomes an important part of the overall evaluation.
Strong businesses require strong financial stewardship, and lenders evaluate both the performance of the company and the financial discipline behind it.
Preparation Creates Financing Options
Being prepared for financing requires more than understanding your own financial condition. It also requires understanding where your financing request fits within the lending marketplace.
In reality, every lender has its own lending philosophy, industry preferences, risk tolerance, and credit parameters.
A loan that does not align with one institution’s lending criteria may be well suited for another. This does not necessarily indicate that the loan request is weak.
It may simply mean the request is being presented to the wrong lender.
Understanding where your financing request fits or the type of financing that fits your needs can save valuable time, reduce frustration, and significantly improve the likelihood of approval.
This is where the difference between reactive and proactive financial management becomes significant.
A reactive business begins looking for options after capital becomes necessary. A prepared business understands its financial position, potential financing needs, and available alternatives before the need becomes urgent.
Equally important is maintaining current financial information. Profit and loss statements, balance sheets, debt schedules, accounts receivable and payable aging reports, work-in-progress reports, projections, and business plans should never be assembled only after financing becomes urgent.
Businesses that maintain these documents throughout the year are better positioned to respond quickly when opportunities arise.
Financing Should Support Growth—Not Rescue It
One of the biggest mistakes business owners make is waiting until financing becomes an emergency.
When equipment unexpectedly fails, cash flow tightens, an acquisition becomes available, or an attractive project suddenly appears, owners often begin searching for capital under intense time pressure.
Unfortunately, urgency rarely improves financing options.
Preparation does.
The strongest financing decisions are made before the need becomes immediate. Businesses that establish banking relationships early, understand their financial position, monitor performance regularly, and prepare documentation in advance place themselves in a far stronger position when an opportunity—or challenge—presents itself.
Preparation creates flexibility. Flexibility creates options. And options create better business decisions.
The Competitive Advantage Many Business Owners Overlook
Every successful business relies on preparation.
Growth begins with planning. Resources are organized before opportunities are pursued. Systems are put in place before demand increases. Strategies are developed before major decisions are made.
Business financing deserves the same disciplined approach.
This is also where business finance and organizational performance intersect.
The principles behind From Reactive to Proactive – The Preparation-Driven Performance System™ are based upon a simple premise: organizations perform better when preparation occurs before the moment of need.
Financing is a powerful example.
A reactive organization begins searching for capital after the need has arrived. A preparation-driven organization understands its financial condition, monitors its performance, anticipates potential capital requirements, and develops financing relationships and options before they are needed.
That does not guarantee that every financing request will be approved. Preparation rarely guarantees an outcome.
What preparation does is improve the probability of a better outcome.
And perhaps more importantly, it improves an organization’s ability to make better decisions when circumstances change.
The objective should never be simply to qualify for financing.
The objective should be to build a business that is financially prepared enough to have options.
Because when an unexpected challenge emerges—or an unexpected opportunity appears—the question should not be:
“Where can we find the money?”
A better question is:
“Which of our available options makes the most sense?”
That is the difference between reacting to a financial need and being prepared for one.
And that is what preparation-driven performance looks like in business finance.
Todd A. Smith is a Business Performance & Finance Strategist, owner of Royce Joseph Capital LLC, and creator of the Preparation-Driven Performance System™. For more than 15 years, he has helped businesses nationwide secure financing ranging from working capital and equipment loans to commercial real estate and SBA financing. Todd serves on the Board of Directors of the Metropolitan Builders & Contractors Association of New Jersey and is a National Trustee of the National Association of Home Builders Sales & Marketing Council. He is the author of Navigating the Lending Maze and a nationally recognized speaker on business performance, strategic preparation, and commercial finance.